The short version
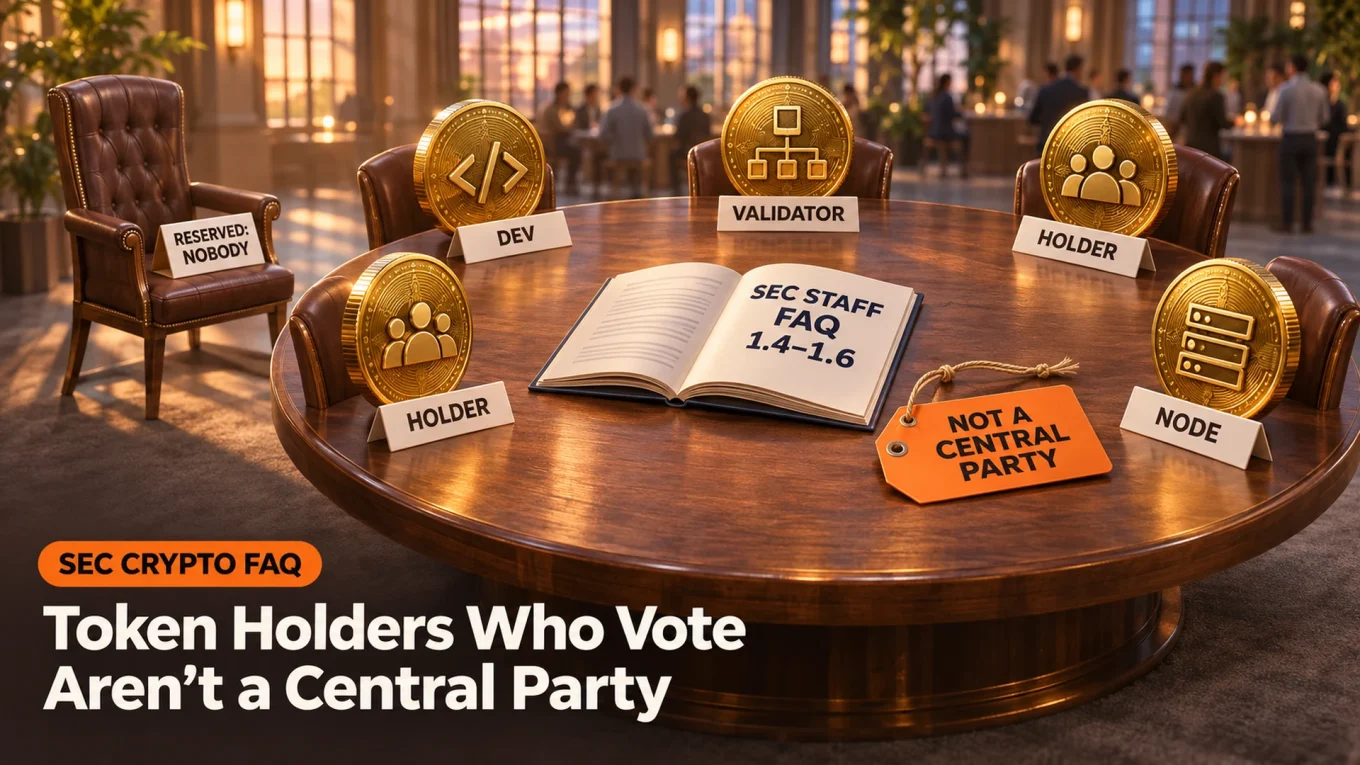
- The SEC crypto FAQ added questions 1.4 to 1.6 on November 2, saying unaffiliated token holders voting through open, rules-based governance are generally not a “central party”.
- That phrase decides whether a token can be a digital commodity under the SEC’s March taxonomy, but these are staff views with no legal force, and a future SEC can rewrite them.
- Next: the midterms today and the Senate’s return on November 6, which decide whether the CLARITY Act ever puts a decentralization test into law. Follow Base Camp on X to see each step first.
The SEC crypto FAQ got three new answers on Monday, and they go after the oldest question in DeFi: if token holders vote on a protocol, does that make them the boss? SEC staff now say mostly no.
The Division of Corporation Finance added questions 1.4, 1.5 and 1.6 to its crypto FAQ on November 2. All three explain one phrase from the SEC’s token taxonomy, “central party”, and that phrase decides whether a token can count as a digital commodity rather than a security.
Miles Jennings of a16z crypto read Question 1.4 as room for DAOs to keep decentralized governance while using legal entities such as DUNAs:

The SEC just released a helpful new FAQ to clarify its token taxonomy further.
🔹Q 1.4 – Establishes that systems can maintain decentralized governance and make use of legal entities like DUNAs.
🔹Q 1.5 – Distinguishes between permissioned and permissionless systems.
🔹Q 1.6
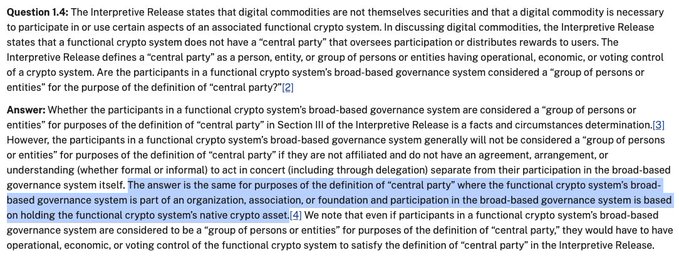
What the SEC Crypto FAQ Now Says About Governance
In short: a broad group of unaffiliated token holders voting through open, rules-based governance is generally not a central party.
That matters because of the interpretation the SEC issued on March 17. It sorts tokens into five groups: digital commodities, digital collectibles, digital tools, stablecoins and digital securities. A digital commodity sits on a “functional crypto system” with no central party, defined as anyone with “operational, economic, or voting control” of the network. DeFi lawyers have asked since March whether a DAO vote counts as that kind of control.
Question 1.4 answers it. Voters generally are not a “group of persons or entities” if they “are not affiliated and do not have an agreement, arrangement, or understanding (whether formal or informal) to act in concert (including through delegation)” outside the vote itself. The answer stays the same when the governance sits inside a foundation or association and voting depends on holding the governance token.
The footnotes set the bar. Proposals, debates, votes and results must be public. The rules can’t be changed by one stakeholder or a coordinated bloc. And voting power can’t pile up with one holder or a group of insiders, delegation included.
Sponsored · Affiliate link
Save 20% on fees trading on WEEX
Base Camp may earn a commission if you sign up. It never affects what we write.
What Counts as Control?
Question 1.5 lists it. A central party “oversees participation” when it alone can grant or limit access, change how upgrades are voted on, pick who validates transactions, change the code, reverse transactions or revoke access.
Two setups pass. Either every material part of the network runs on code with no human discretion, or any discretion left goes only through the broad token-holder vote. A foundation can still be a central party over something else, staff note, for example by setting the parameters of apps built on the network.
Question 1.6 separates two words that often get mixed up. “Functional” means the token can be used as the network is programmed. “Decentralized” means nobody holds control. A functional network with a digital commodity has “characteristics of decentralization”, but how much can vary.
SIDE TRAIL: Most Crypto Assets Are Not Securities, SEC Chair Says. Treasury Won’t Wait for Congress
Why It Matters for Token Holders
It hands DeFi teams a checklist. A protocol run by open token-holder votes, the model behind names like Uniswap and Aave, now has a written staff view on how its token can sit outside securities law. Teams that use a legal wrapper for their DAO get cover too, as long as the wrapper itself doesn’t steer the network.
The limit is in the first paragraph of the SEC crypto FAQ page. These are staff views that “have no legal force or effect”. The Commission “has neither approved nor disapproved their content,” and a future SEC can rewrite them. Only the CLARITY Act, the market structure bill stuck in the Senate, would put a decentralization test into law.
Markets didn’t notice. UNI trades at $6.99 at the time of writing, down 3.8% in 24 hours, and AAVE is at $126, down 6.4%, while Bitcoin slipped 2% to $76,924. Rules like these move listings and launches over months, not prices overnight.
TRAIL MAP: DeFi Basics: Swaps, Liquidity Pools and Impermanent Loss
Today’s midterms decide who runs Congress next year, and with it how long the decentralization test stays a staff FAQ instead of a law.
Satoshi Flipper has more than 20 years of trading experience, starting in stocks before moving into crypto in 2017, and holds an MBA from the Kellogg School of Management. The edge is reading the economic data: rate decisions, inflation, jobs numbers, earnings and the US markets that move Bitcoin.
More from Satoshi Flipper